


Credit Invisibility: What It Means and How to Fix It
Being "credit invisible" means having no credit history or score, which makes it difficult for lenders to evaluate your financial reliability. To fix this, you can use credit-builder services or tools, like Experian Boost, to report regular bill payments, such as rent and utilities, to credit bureaus. By doing so, you will begin to establish a credit history.
Transcript
ELLEN:
Some of you may be watching this and saying, I don't have a credit score.
A number of people actually don’t. To have a credit score, you need some history of borrowing and repayment.
Unfortunately, not having credit history can be just as challenging as having bad credit.
ELLEN:
That’s because lenders don’t know how to evaluate you. They can’t tell whether you’re likely to pay your bills back or not—you’re kind of a blank slate.
In the industry, people with no credit history are often called “credit invisible.”
So what can you do if you don’t have a credit score—or even if you have a low one?
ELLEN:
There are a number of services that work like a reverse loan:
You pay money every month, and at the end, they report those payments to the credit bureau. They take a fee, and you get your money back. It’s not a bad way to start building credit—but it is expensive.
ELLEN:
The good news? Bureaus are starting to recognize how important it is for people to have credit.
Experian, in particular, has led the charge with tools like Experian Go and Experian Boost, which let you:
• Create a credit record
• Connect your bank account
• Build credit from things you're already paying—like rent, utilities, cell phone bills, even Netflix
More in this series
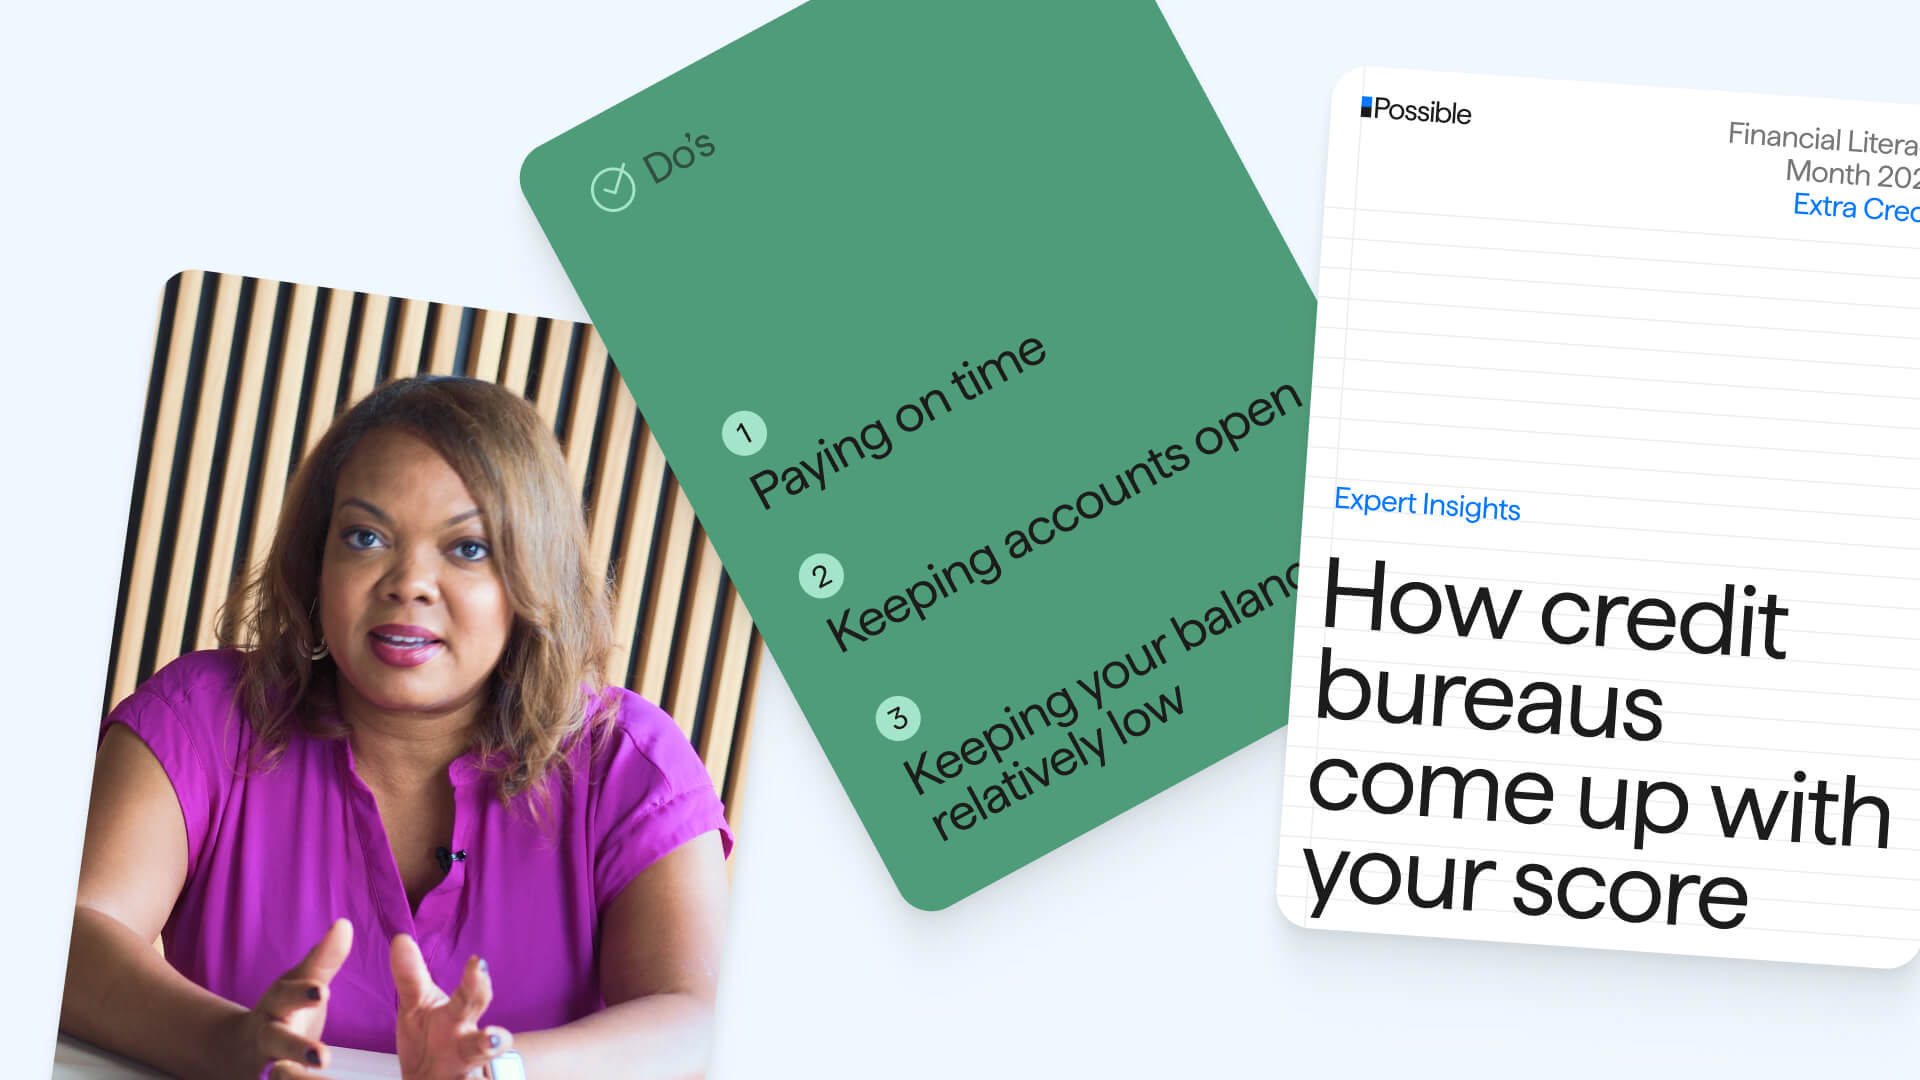
What Impacts Your Credit Score?
Your credit score can feel like a mystery—because in many ways, it is. In this quick breakdown, Legal & Finance Expert, Daynor, shares what really goes into your score, what improves it, what drags it down, and how to actually check it. Whether you’re just starting or trying to bounce back, this is info worth knowing.
1:31
1:31
What Impacts Your Credit Score?
Your credit score can feel like a mystery—because in many ways, it is. In this quick breakdown, Legal & Finance Expert, Daynor, shares what really goes into your score, what improves it, what drags it down, and how to actually check it. Whether you’re just starting or trying to bounce back, this is info worth knowing.
Does Taking Out a Loan Improve Your Credit?
Will taking out a loan help your credit? It might—but not always in the way you think. In this episode of Credit Diaries, Ellen Falbo, our Chief Credit Officer, breaks down what actually improves your credit—and why taking on debt you don’t need could end up costing more than it’s worth.
1:09
1:09
Does Taking Out a Loan Improve Your Credit?
Will taking out a loan help your credit? It might—but not always in the way you think. In this episode of Credit Diaries, Ellen Falbo, our Chief Credit Officer, breaks down what actually improves your credit—and why taking on debt you don’t need could end up costing more than it’s worth.
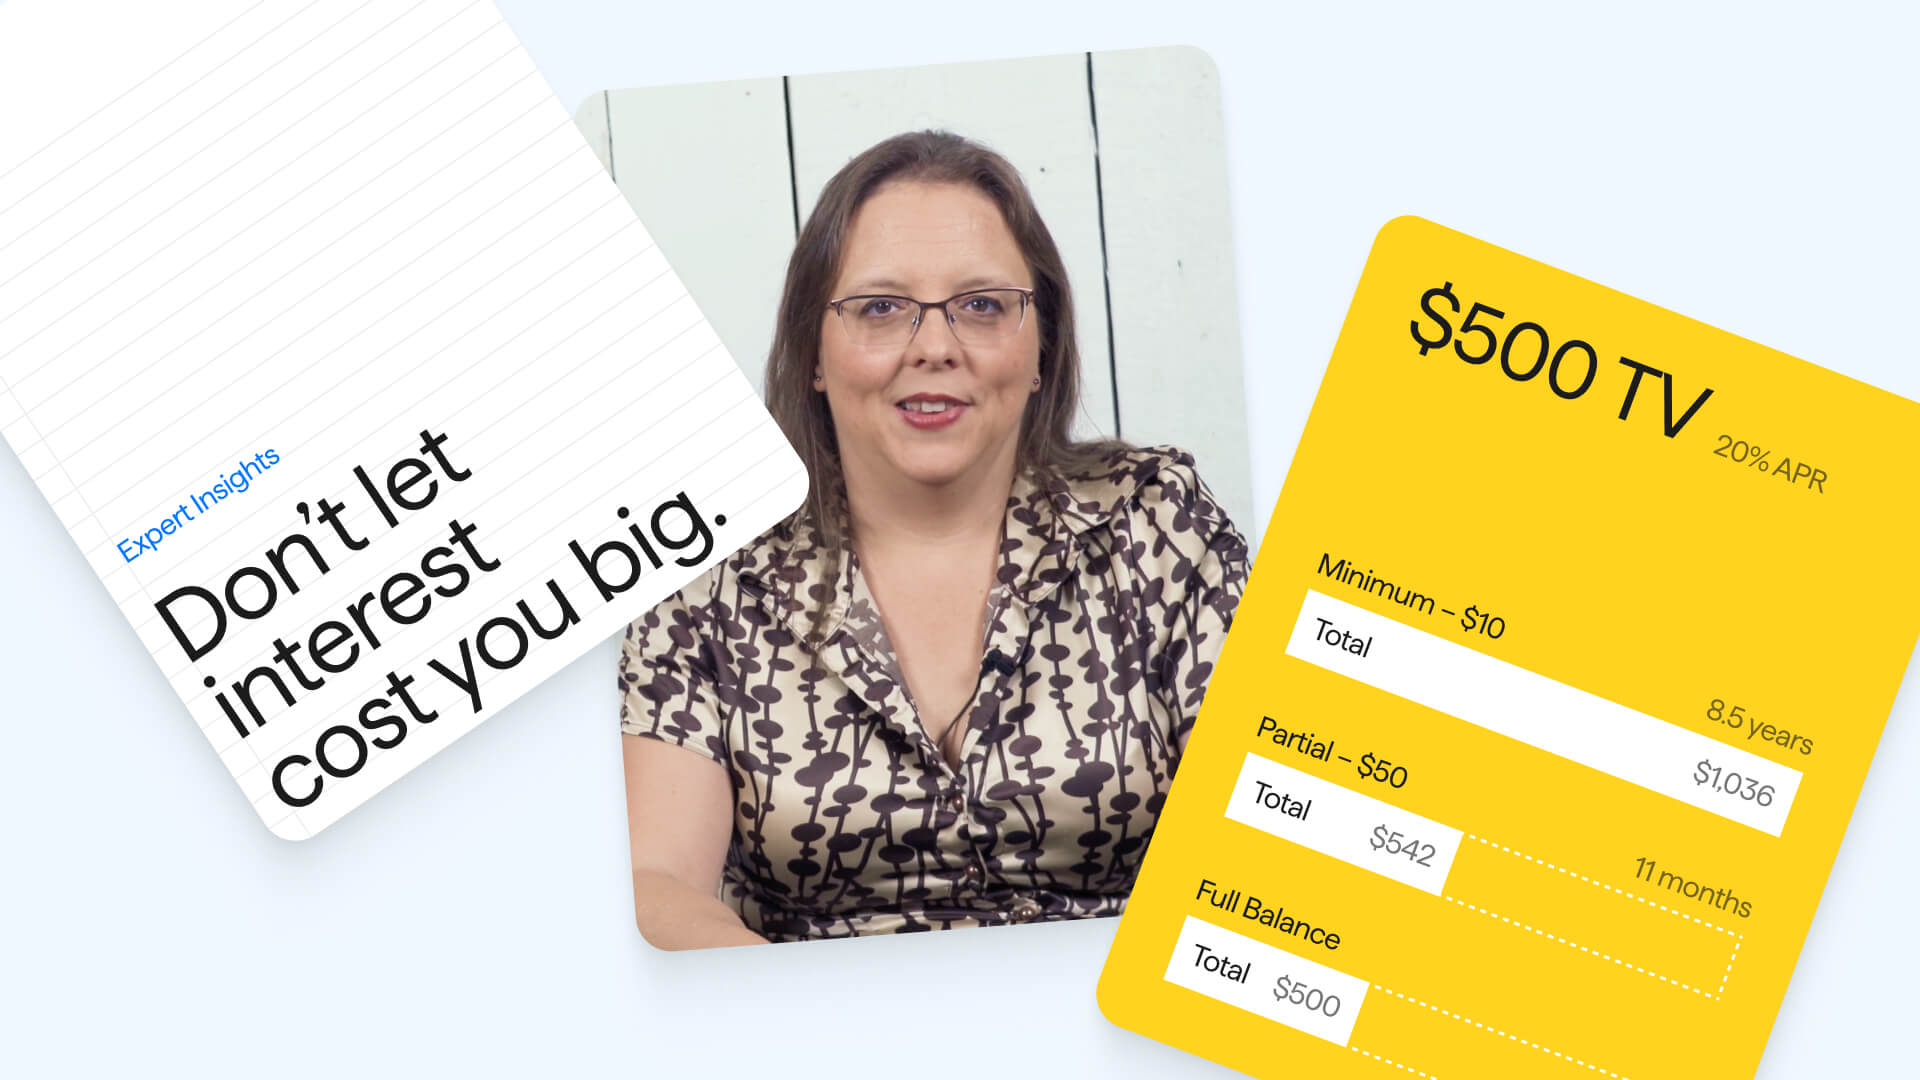
How Credit Card Interest Works
How much does that $500 TV really cost? In this Extra Credit video, Chief Credit Officer Ellen Falbo walks through three common ways people pay off credit cards—and how interest can quietly double the price of everyday purchases.
1:07
1:07
How Credit Card Interest Works
How much does that $500 TV really cost? In this Extra Credit video, Chief Credit Officer Ellen Falbo walks through three common ways people pay off credit cards—and how interest can quietly double the price of everyday purchases.

Avoid Credit Card Interest Using the Grace Period
Learn how to use credit cards without paying interest. Ellen explains the “grace period,” statement balances, and smart strategies to stay out of debt.
1:31
1:31
Avoid Credit Card Interest Using the Grace Period
Learn how to use credit cards without paying interest. Ellen explains the “grace period,” statement balances, and smart strategies to stay out of debt.
Do You Need to Carry a Balance to Build Credit?
You don’t need to carry a balance to build credit. In this quick myth-busting episode, Ellen Falbo, Chief Credit Officer at Possible, explains how credit utilization really works—and how to boost your score without paying interest.
1:06
1:06
Do You Need to Carry a Balance to Build Credit?
You don’t need to carry a balance to build credit. In this quick myth-busting episode, Ellen Falbo, Chief Credit Officer at Possible, explains how credit utilization really works—and how to boost your score without paying interest.
Fix Credit Report Errors and Dispute Inaccuracies
Learn how to fix credit report errors and dispute inaccurate information under the Fair Credit Reporting Act. Legal & Finance expert, Daynor, explains your rights and where to start.
0:46
0:46
Fix Credit Report Errors and Dispute Inaccuracies
Learn how to fix credit report errors and dispute inaccurate information under the Fair Credit Reporting Act. Legal & Finance expert, Daynor, explains your rights and where to start.

A New Way To Think About Your Credit Score
Is your credit score 640 or 639? It might not matter as much as you think. In this episode of Credit Diaries , Ellen Falbo, our Chief Credit Officer, breaks down credit myths, scoring models and what actually counts for Sue, a Possible member since 2022.
1:00
1:00
A New Way To Think About Your Credit Score
Is your credit score 640 or 639? It might not matter as much as you think. In this episode of Credit Diaries , Ellen Falbo, our Chief Credit Officer, breaks down credit myths, scoring models and what actually counts for Sue, a Possible member since 2022.
All products are subject to eligibility and approval by Possible Financial Inc. dba “Possible Finance” and “Possible” or its banking partner Coastal Community Bank. Eligibility for a product is not guaranteed.
For Loans, Possible Finance has direct lending licenses in AK, CA, HI, ID, UT and WA. Idaho Residents: License #RRL-10073; Louisiana Residents: License #1697898; Ohio Residents: License #ST.760161.000; Washington License #530-CC/SL-111888. California Residents: Possible Finance is licensed by the Department of Financial Protection and Innovation, pursuant to the California Deferred Deposit Transaction Law, License #10DBO-105848.
Loans in AL, AR, AZ, DE, FL, IA, IN, KS, KY, LA, MI, MO, MS, MT, NC, NE, NH, NV, OH, OK, OR, RI, SC, TN, TX, VA, VT, and WY are made by Coastal Community Bank, and serviced by Possible Finance. Texas Residents: Possible Finance is a licensed Credit Access Business; License #1800061850-160823.
*Funding typically occurs within seconds; ACH transfers take 1-2 business days. Instant Delivery fee may apply in select states.
^Loan amounts & structure vary by state. Max amount not typical.
°Savings since 2017 includes fees Possible doesn't charge (e.g., NSF, rollover) plus reduced costs from customers borrowing less frequently than typical payday loan users, assuming customers would otherwise have faced industry-average fees and borrowing rates. Sources: internal data; state regulatory data; CFPB (Pub. No. 2023-9); Pew ("Payday Lending in America," 2013); CRL ("Down the Drain," 2025). Individual results may vary.
¨See possiblefinance.com/samplepaymentschedules for rates & terms examples.
ˇReal customer compensated or incentivized. Results vary.
˘Possible Loans offer up to 29 days of payment flexibility from original due date.
All trademarks and brand names are property of their respective owners. Use of them does not imply any affiliation with or endorsement by them.
If you have questions or concerns, please contact the Support Team at support.possiblefinance.com
Mailing Address: Possible Finance, PO Box 98686, Las Vegas, NV 89193
Possible Financial Inc. © 2026 - NMLS #1697898
All products are subject to eligibility and approval by Possible Financial Inc. dba “Possible Finance” and “Possible” or its banking partner Coastal Community Bank. Eligibility for a product is not guaranteed.
For Loans, Possible Finance has direct lending licenses in AK, CA, HI, ID, UT and WA. Idaho Residents: License #RRL-10073; Louisiana Residents: License #1697898; Ohio Residents: License #ST.760161.000; Washington License #530-CC/SL-111888. California Residents: Possible Finance is licensed by the Department of Financial Protection and Innovation, pursuant to the California Deferred Deposit Transaction Law, License #10DBO-105848.
Loans in AL, AR, AZ, DE, FL, IA, IN, KS, KY, LA, MI, MO, MS, MT, NC, NE, NH, NV, OH, OK, OR, RI, SC, TN, TX, VA, VT, and WY are made by Coastal Community Bank, and serviced by Possible Finance. Texas Residents: Possible Finance is a licensed Credit Access Business; License #1800061850-160823.
*Funding typically occurs within seconds; ACH transfers take 1-2 business days. Instant Delivery fee may apply in select states.
^Loan amounts & structure vary by state. Max amount not typical.
°Savings since 2017 includes fees Possible doesn't charge (e.g., NSF, rollover) plus reduced costs from customers borrowing less frequently than typical payday loan users, assuming customers would otherwise have faced industry-average fees and borrowing rates. Sources: internal data; state regulatory data; CFPB (Pub. No. 2023-9); Pew ("Payday Lending in America," 2013); CRL ("Down the Drain," 2025). Individual results may vary.
¨See possiblefinance.com/samplepaymentschedules for rates & terms examples.
ˇReal customer compensated or incentivized. Results vary.
˘Possible Loans offer up to 29 days of payment flexibility from original due date.
All trademarks and brand names are property of their respective owners. Use of them does not imply any affiliation with or endorsement by them.
If you have questions or concerns, please contact the Support Team at support.possiblefinance.com
Mailing Address: Possible Finance, PO Box 98686, Las Vegas, NV 89193
Possible Financial Inc. © 2026 - NMLS #1697898
All products are subject to eligibility and approval by Possible Financial Inc. dba “Possible Finance” and “Possible” or its banking partner Coastal Community Bank. Eligibility for a product is not guaranteed.
For Loans, Possible Finance has direct lending licenses in AK, CA, HI, ID, UT and WA. Idaho Residents: License #RRL-10073; Louisiana Residents: License #1697898; Ohio Residents: License #ST.760161.000; Washington License #530-CC/SL-111888. California Residents: Possible Finance is licensed by the Department of Financial Protection and Innovation, pursuant to the California Deferred Deposit Transaction Law, License #10DBO-105848.
Loans in AL, AR, AZ, DE, FL, IA, IN, KS, KY, LA, MI, MO, MS, MT, NC, NE, NH, NV, OH, OK, OR, RI, SC, TN, TX, VA, VT, and WY are made by Coastal Community Bank, and serviced by Possible Finance. Texas Residents: Possible Finance is a licensed Credit Access Business; License #1800061850-160823.
*Funding typically occurs within seconds; ACH transfers take 1-2 business days. Instant Delivery fee may apply in select states.
^Loan amounts & structure vary by state. Max amount not typical.
°Savings since 2017 includes fees Possible doesn't charge (e.g., NSF, rollover) plus reduced costs from customers borrowing less frequently than typical payday loan users, assuming customers would otherwise have faced industry-average fees and borrowing rates. Sources: internal data; state regulatory data; CFPB (Pub. No. 2023-9); Pew ("Payday Lending in America," 2013); CRL ("Down the Drain," 2025). Individual results may vary.
¨See possiblefinance.com/samplepaymentschedules for rates & terms examples.
ˇReal customer compensated or incentivized. Results vary.
˘Possible Loans offer up to 29 days of payment flexibility from original due date.
All trademarks and brand names are property of their respective owners. Use of them does not imply any affiliation with or endorsement by them.
If you have questions or concerns, please contact the Support Team at support.possiblefinance.com
Mailing Address: Possible Finance, PO Box 98686, Las Vegas, NV 89193
Possible Financial Inc. © 2026 - NMLS #1697898